
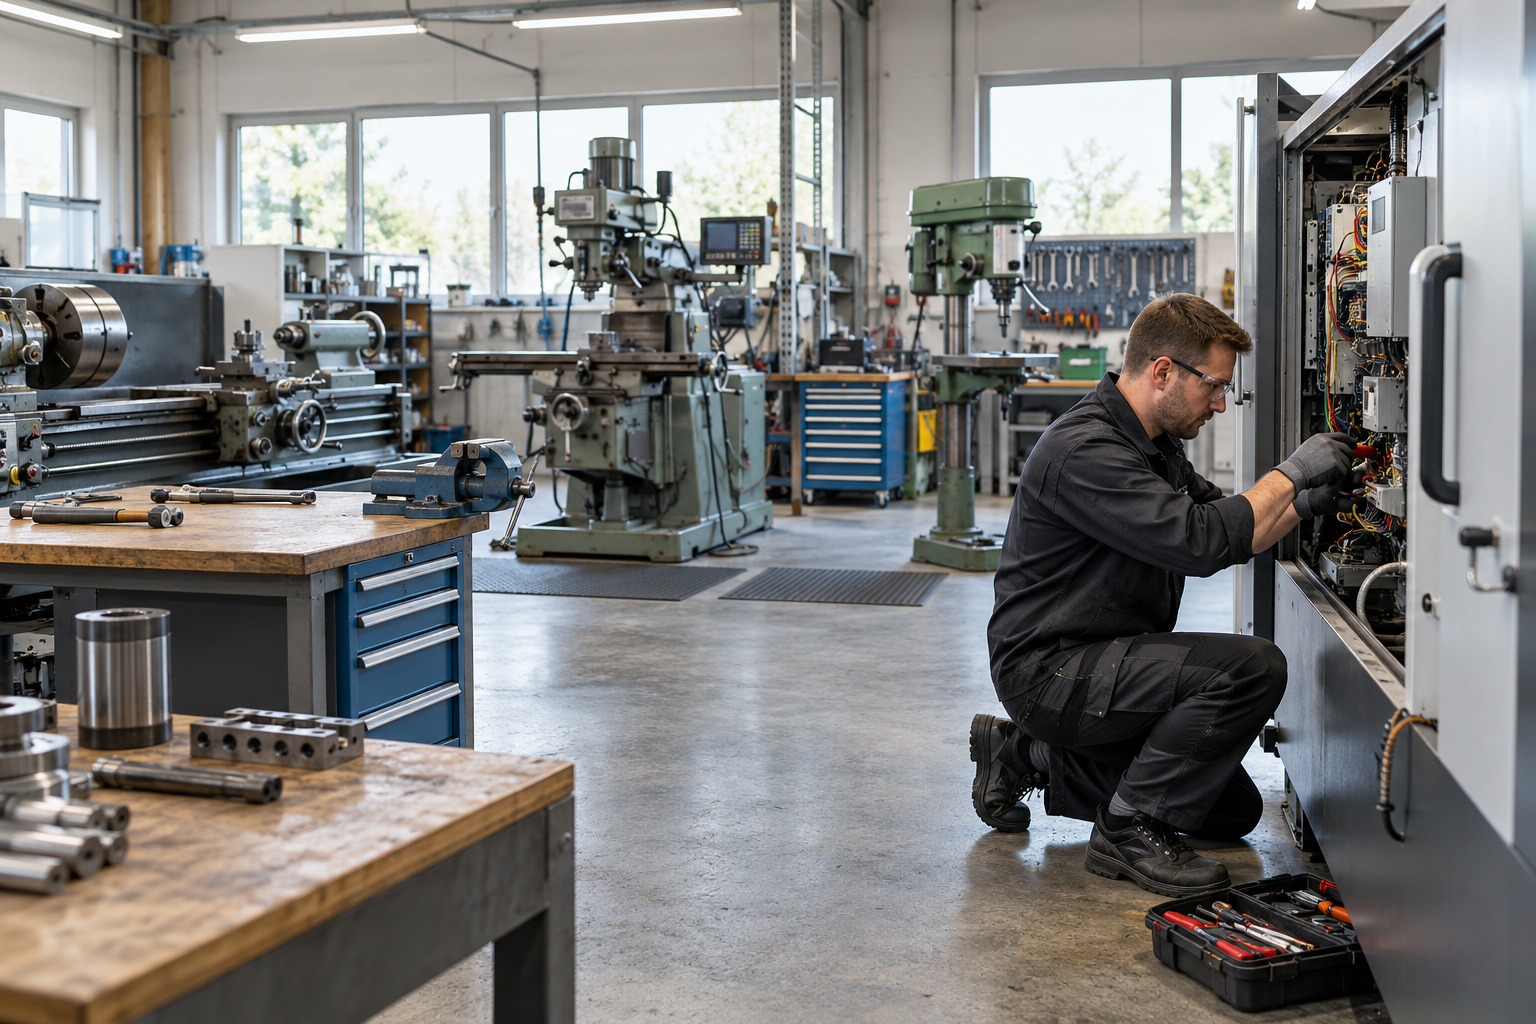
Workshop Equipment Insurance in Germany:
A Practical Guide
1. How Can I Insure My Workshop Equipment Against Breakdown and Damage at a Branch in Germany?
A damaged machine creates two problems: the cost of repairing it and the disruption while it is unavailable. For an international company operating a workshop in Germany, there is a third question: does the group’s existing insurance actually cover the German location?
Workshop equipment insurance in Germany usually requires coordinated protection for business contents, machinery breakdown and business interruption. These may be separate policies or modules within a combined contract. The right arrangement depends on your equipment, the causes of damage insured and your existing multinational insurance programme.
2. Which Insurance Covers Workshop Equipment in Germany?
The cause of the loss determines which cover may respond. A fire, an internal mechanical failure and an operating error are different insurance scenarios.
| Risk or asset | Cover to examine | Key point to check |
|---|---|---|
| Fire, burst-pipe water damage or burglary affecting workshop contents | Business contents insurance — Inhaltsversicherung | Insured perils, location, values and security requirements |
| Unexpected physical damage caused by technical failure or operating errors | Machinery insurance — Maschinenversicherung | Internal breakdown cover, insured equipment and exclusions |
| Damage to diagnostic equipment, computers or eligible electronic systems | Electronic equipment insurance — Elektronikversicherung | Equipment classification and overlap with machinery cover |
| Lost earnings and continuing expenses following insured physical damage | Business interruption cover — Betriebsunterbrechungsversicherung | Whether the underlying damage is an insured trigger |
| Mobile equipment used away from the workshop | Mobile machinery cover or an agreed off-site extension | Territory, transport, theft and overnight storage conditions |
The table is a guide to questions you should ask, rather than a guarantee that every policy includes each risk.
Business Contents Insurance: Protection Against External Events
Business contents insurance can cover workshop machinery, tools, stock and other business equipment against agreed risks such as fire, burglary, escape of water, storm and hail. Flood and other natural-hazard protection must be checked explicitly.
Do not assume that “water damage” includes every source of water, or that burglary cover includes every form of theft. Policy definitions matter.
For example, Zurich’s German contents insurance information describes cover for commercial and technical equipment, with protection against specified property risks. Its scope also illustrates why customer property and natural hazards should be checked in the actual contract. [1]
Machinery Insurance: Protection Against Unexpected Physical Damage
Machinery insurance can address unexpected physical damage from operating errors, internal mechanical breakdown or electrical causes. Depending on the wording, damage arising from design or material defects may also be covered, subject to exclusions and any responsibility of a manufacturer or supplier. [2]
This distinction matters: an ordinary property policy covering fire and burglary does not automatically cover an internal machine failure.
Also check the relationship between the policies. Allianz Esa’s published information for stationary machinery, for example, excludes fire, burglary and certain natural hazards from that particular machinery product and points to separate contents insurance. A policy described as “all risks” still has exclusions. [3]
Electronic Equipment Insurance: Check the Classification
Diagnostic devices, measuring equipment and computers may require electronic equipment cover. Such policies can cover physical damage caused by operating errors, short circuits or other agreed events.
Ask how integrated controls are classified: within the machine, under electronic equipment insurance, or under a combined technical policy. Data and software restoration should also be checked separately; physical equipment cover does not automatically provide unrestricted protection for data loss. [4]
Why Equipment Repairs Alone May Not Be Enough
A repaired machine does not compensate your business for the earnings lost while it was out of service.
Business interruption insurance can cover insured loss of profit and continuing operating expenses following a qualifying event. The independent IHK Würzburg-Schweinfurt explains that fire-related interruption cover can address continuing expenses and lost business profit, and specifically highlights machinery delivery times. [5]
The trigger is decisive. Fire-related interruption insurance does not automatically respond to an internal mechanical breakdown. If this is a significant exposure, examine machinery business interruption cover or an appropriate technical insurance extension. [6]
Check the indemnity period, the insured financial basis and any monetary deductible or waiting period. Allow for replacement delivery, installation and commissioning when estimating how long recovery could take.
An Illustrative Example: A CNC Machine Stops Production
Suppose an operating error damages a CNC machine at your German workshop. Repairs cost €28,000 and production is disrupted for four weeks.
Machinery insurance may respond to the physical damage if the cause and equipment are covered. A corresponding business interruption section may address qualifying lost profit and continuing expenses.
Without the appropriate interruption cover, an accepted repair claim could still leave the financial consequences of the shutdown with your company.
This is a hypothetical example, not a documented claim or an assurance of payment. Actual settlement depends on policy terms, deductibles and evidence of loss.
3. Does the Parent Company’s Insurance Cover the German Branch?
Before buying additional insurance, ask your group’s risk manager or broker to confirm the existing arrangement.
Useful questions include:
- Is the German location included, and is the correct company identified as insured?
- Are the workshop activities, equipment values and business interruption exposure declared?
- Does the programme include internal machinery breakdown, or only specified property risks?
- Is there a German local policy, and how does it interact with the master policy?
- Who handles the claim, and which entity receives the payment?
A multinational programme may combine local policies with a master policy. Difference in Conditions (DIC) and Difference in Limits (DIL) provisions can help address differences in cover or limits, subject to their terms. They do not automatically close every gap. Chubb’s technical guidance explains this interaction and the importance of jurisdictional requirements. [7]
The appropriate structure for your German operation requires a review of the actual programme, including relevant regulatory and tax considerations.
4. What Should You Check Before Taking Out Cover?
Equipment Values and Settlement Basis
Prepare an inventory of critical machines and devices, including ownership, age, location and replacement cost.
Ask which valuation basis the insurer requires. Book value is not necessarily the correct insurance value. Also distinguish the sum insured from the settlement basis: the amount declared does not itself guarantee new-for-old compensation after a total loss.
Confirm how freight, installation, foundations and commissioning costs are treated. For leased or financed equipment, check both insurance requirements and the interests of the owner or lender.
Wear, Maintenance and Existing Damage
Insurance should not be treated as a maintenance budget. Normal wear and deterioration are commonly excluded. However, the treatment of resulting damage can differ: Allianz’s published machinery information distinguishes excluded wear from potentially insured consequential physical damage. [2]
Ask specifically about worn components, consumables, existing defects and damage associated with overdue servicing. Keep inspection and maintenance records.
Equipment Outside the Workshop
Do not assume that cover at a declared German address follows equipment to customer premises or another group location.
Check off-site use, transport, loading and unloading, temporary storage and theft separately. Some technical products offer extensions for mobile machinery outside the insured premises, illustrating that this protection may need to be expressly arranged. [6]
5. How Much Does Workshop Equipment Insurance in Germany Cost?
A reliable premium estimate requires details of the risk. Equipment values, workshop activities, location, previous losses, chosen cover and deductibles all matter.
Compare quotations using the same scope. A cheaper offer may exclude a critical cause of loss or provide a shorter interruption indemnity period.
For an initial assessment, prepare your equipment inventory, German site address, existing policy documents, claims history and an estimate of the financial impact if your most important machine becomes unavailable. [1]
Protect the Equipment Your German Operation Depends On
For a review of workshop equipment insurance for your German branch, contact Leeb Versicherungsmakler in Munich. Please provide your equipment inventory and existing insurance documents so the discussion can focus on the actual risks and potential coverage gaps.
Sources
- Zurich Germany: Business contents insurance
- Allianz: Machinery insurance
- Allianz Esa: Stationary machinery insurance
- Allianz: Electronic equipment insurance
- IHK Würzburg-Schweinfurt: Business insurance guidance
- Allianz: Combined technical insurance
- Chubb: Helping Multinational Clients Navigate the Nuances of Master Policy DIC/DIL Clauses
Sources checked: 12 October 2026. IHK guidance is independent of individual insurers. Insurer product pages illustrate specific coverage arrangements and are not universal policy standards.
Your German workshop depends on its equipment.
Does your insurance cover what happens when it stops?
FAQs about workshop equipment insurance
Your content goes here. Edit or remove this text inline or in the module Content settings. You can also style every aspect of this content in the module Design settings and even apply custom CSS to this text in the module Advanced settings.
Is workshop equipment insurance compulsory in Germany?
These property and machinery covers are generally voluntary. However, leases, financing agreements or other contracts may require particular insurance. Check the obligations applying to your equipment and premises.
Will the landlord's insurance cover our machines?
Do not assume so. Ask for confirmation of what is insured under the building policy and arrange appropriate protection for your company’s equipment.
Can contents, machinery and interruption cover be combined?
Yes, combined arrangements are available. Check the insured property, causes of loss and interruption triggers within each section. A single contract still needs a detailed coverage review.
Does machinery insurance cover every breakdown?
No. A malfunction without insured physical damage may fall outside the cover. Wear, maintenance costs and other exclusions must be considered, and the treatment of consequential physical damage depends on the wording.
0 Comments